Adorian Demeter, Founder and General Manager, Dai-Tech (owner of the nJoy brand)
The evolution of storage, the development of the prosumer segment and also exports have ensured a 39% growth for the company distributing systems dedicated to the industry, such as UPS and inverters, says Adorian Demeter, Founder and General Manager, Dai-Tech (owner of the nJoy brand). He also explains to us to what extent equipment assembled and certifi in Europe can compete with those from China.
What were the main results of the rst half of 2026? What are the targets for the whole of 2026?
The fi rst half of 2026 was the best period in the company’s recent history. We increased sales by approximately 39% compared to the same period last year. As a benchmark, 2025 ended with 16.8% above 2024, and over the last three years combined we are at about 35%. We have practically doubled our pace. The growth is cross-segment and we consider it healthy. Export remains an important component, but here a clarifi cation is needed so that there is no misunderstanding. In the traditional segment, that of UPS and power supply protection, exports reached about 54% of sales this year, compared to 49% last year. We are known there and have been working on foreign markets for many years: nJoy products are currently sold in 16 countries, from Europe to the Caucasus, North Africa and the Middle East. In terms of solar solutions, we sell mainly in Romania and only this year have we been working on increasing exports. It is a direction that we are betting on, but we are at the beginning. In the product area, the important step of the semester was the entry into Commercial & Industrial (C&I), with equipment that works with storage between 64 and 112 kWh, and in 2027 we will also move up to higher capacities. For us, it is a logical extension: we come from power protection, where we are leaders in the Romanian market, and we reach systems that produce, store and manage energy. In C&I, the two competencies meet. Also during this period, we launched the RUNA UPS series.
By the end of the year, three-phase inverters based on low-voltage technology will follow, as well as two things from the uninterruptible power supply area: a new generation of UPS for home use, with functionalities that do not currently exist in the home UPS segment, and UPS for industrial environments, with capacities of up to 400 kW per rack. We will talk about them at the time of launch.
The target for 2026 is a growth of at least 35% at the company level.
What will be the main growth directions of the company in the coming period?
We have three directions: Commercial & Industrial, storage and foreign markets. It is clear how the market is moving from simple residential systems to solutions in which production, storage, energy management and continuity of supply come as a package. The customer no longer buys four separate things.
About China: like almost the entire industry, we rely on manufacturing capacities in Asia. However, the local contribution is significant, because the product specifi cation, development, testing and adaptation to the requirements of the European market are done here. On the production side itself, very few players in Europe can say otherwise, regardless of the brand on the casing. Competition on price and effi ciency took place there, and Asian manufacturers brought the cost of technology down. It is a reality known to everyone in the industry and diffi cult to dispute. What has changed is that a second discussion has emerged, parallel to the commercial one. The inverter is no longer a simple converter. It is a permanently connected piece of equipment, which is updated remotely and which sees operational data from the installation. When many new systems in Europe depend on a small number of suppliers, a risk accumulates there that the European institutions have already signaled. The European direction seems correct to us. The real question is how it is transformed into criteria. If everything is reduced to the country of assembly, some costs will increase and that’s about it, because the risk does not lie in the casing. It lies in the software, in the update channel and in the place where the data arrives. If, on the other hand, transparency and auditability on the software side, control over updates, interoperability and an entity that is legally responsible in the Union are required, then the objective is indeed achieved. We say this knowing that such a transition requires adaptation from everyone, including us. What we can claim today: we are a European company and we are legally responsible in the EU for what we put on the market; the equipment is TÜV certifi ed, so verifi ed by a third party, not just declared by us; we off er an open API, so that the installer or customer can integrate their system into their own energy management platform, without being locked into a closed ecosystem; and we have local technical support, with people responding from Romania. For an industrial customer, the last two things matter significantly more than a fraction of a percentage increase in one specifi cation or another, because when the installation stops, that extra bit doesn’t help him at all. What would help from Europe: clear criteria, published in advance, and predictability. Nobody invests in their own production capacity if they don’t know what the rules will look like in fi ve or ten years. Without this, we remain at the level of declarations, and dependence does not decrease, but only becomes more expensive.
How did the main market segments evolve in 2026?
The market is maturing. The number of prosumers in Romania has exceeded 330,000, and their cumulative installed power has exceeded that of dispatchable photovoltaic parks. Distributed production has come to matter for the system, it is no longer a niche.
A detail from the same data shows where the market is going: companies represent about a tenth of the number of prosumers, but they own almost half of the installed power. The growth in MW is moving from the roof of the house to the roof of the hall. That is why I have entered C&I now.
Something else has changed in residential. People no longer ask primarily about panels, they ask about batteries and how to control their consumption. The reason is economic: the energy consumed directly is worth much more than that injected into the grid, and the difference has increased. On the market, about a quarter of prosumers also have storage. In our country, practically all hybrid systems we deliver start with batteries.
The third element, less discussed, is the transition to the allocation of connection capacity through auctions, instead of the first-come, first-served principle. Connection has become a limited resource. For an industrial customer, the consequence is direct: solutions that do not require new network capacity, i.e. self-consumption, storage, microgrid, become much more attractive. That’s where we position ourselves.
What were the biggest challenges of 2026, from your perspective?
The structural problems of the market are known and relate to the gap between how quickly capacities are installed and how quickly the grid can take them over. For us in the company, the challenges of the year were diff erent. The fi rst is the pace. We come from an industry where a product lives for seven to ten years. In solar energy, the life cycle of a product is two to three years. Everything changes: the speed of development, testing, certifi cation, the way you keep stock. We have invested in technology and in the way we work, and the result is a clear acceleration: in 2026 and the fi rst part of 2027 we bring seven new product families to our portfolio, signifi cantly more than we have launched in other similar periods. We are not talking about power variants from the same series, but about distinct families, each with its own development, testing and certifi cation cycle. The second is notoriety. We are the market leaders in Romania for UPS. We are still a relatively new name in solar. What we constantly see is that the discussion ends only after the fi rst installation. The installer who installed us once returns satisfi ed and open to a longterm collaboration, because the product does its job in the fi eld and has someone to answer him when a question arises. The hard part is getting to the fi rst installation. It is not solved with a campaign; it is solved over time and with a lot of fi eld work. The third comes from the second. Part of the market chooses strictly by price, and nJoy has never set out to be the price leader. The quality we put into the product is not supported by the lowest price on the market. Our job is to make the cost visible throughout the life of the system: what warranty does it have, who services it, what happens in the fourth year when a problem arises and who do you call then. It is a harder discussion than the one about price, but it is fair to the person who stays with the system at home or in the hall for twenty years.
How do you see the evolution of the energy market in Romania, in light of the current situation?
The crisis we went through was not a renewables crisis, even if it was read that way. The drought hit hydro and nuclear at the same time, two sources on which we structurally rely and which both depend on water. We did not lack production capacity. We lacked fl exibility. The defi cit did not appear at noon. It appeared in the evening. The most eloquent thing in the whole crisis was the authorities’ call to consumers, companies and prosumers to voluntarily reduce consumption in the evening hours. It is a manual solution to a problem that already has an automatic solution.
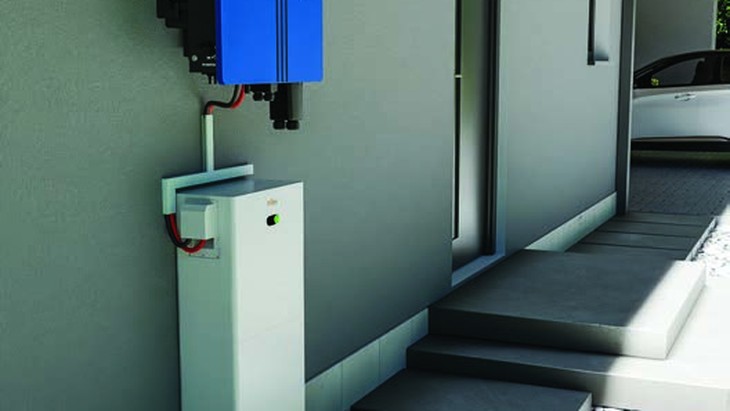
A correctly sized storage system does exactly this, without the user giving up anything: it charges the battery when energy is cheap and abundant, then supplies consumption in the evening, at peak times. If some of the more than 330,000 prosumers had 10-20 kWh of storage, the system would gain a resource comparable to a power plant in the critical range. Distributed, already connected, without new authorizations and without new network capacity.
What we think we need, in this order: Distributed storage at the consumer. It is the fastest form of flexibility to install and the only one that does not depend on new connection capacity.
Correct price signals. A battery optimizes what is asked of it. Today it is asked to reduce the bill. With dynamic tariffs and remunerated flexibility, the same battery would also work for the system.
Aggregation and energy communities, so that prosumers become a balancing resource. The regulatory framework has begun to open up; it must be carried through to the end.
Predictability. The current compensation mechanisms are guaranteed for a limited period. Nobody puts money into a system that lasts twenty years today without knowing what will happen after that.
The option that new prosumers be connected only if they also have a storage component is also being discussed. It must be said openly that we have an interest in this discussion, because we sell storage solutions, so our position is read into this amendment. The direction seems correct to us for the system. But an obligation introduced without a support mechanism and without a transition period makes access more expensive and slows down the market exactly when we need it most. The incentive works better than coercion, especially since the investment economy moves towards storage anyway, on its own.
Romania can now move from the status of a market that installs photovoltaic equipment to that of a market that operates an energy system. The difference is not seen in the installed megawatts, but in how much of the energy produced ends up being used at the time when the system really needs it.
_____________________________________________
The interview also appeared in the print edition of Energynomics Magazine, Q3 2026 issue.
In order to receive the printed or electronic issue of Energynomics Magazine, we encourage you to write us at office [at] energynomics.ro to include you in our distribution list. All previous editions are available HERE.