

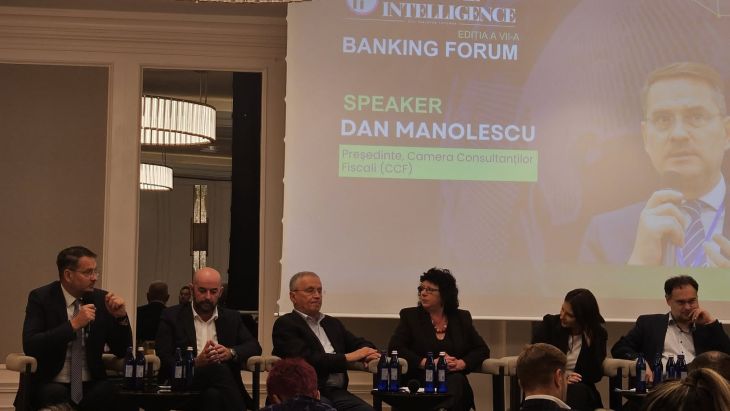
The bill on limiting the deductibility of expenses between companies in the same group would lead to double taxation of some amounts, including in the case of Romanian groups, and could increase financing costs and reduce Romania’s attractiveness for investments, warns the Chamber of Tax Consultants (CCF), in a statement.
“The Chamber of Tax Consultants supports any approach that strengthens tax compliance, but it must be built on predictable, proportionate rules and aligned with international standards. We want the subject to be analyzed together with the Government, ANAF and the business environment, before a decision that could affect Romania’s credibility in the OECD accession process,” said Dan Manolescu, president of the Chamber of Tax Consultants, in a statement.
According to the organization, the draft law PL x 694/2026, adopted by the Senate on October 21, 2026 and currently under debate in the Chamber of Deputies, the decision-making body, proposes that, as of January 1, 2027, expenses for management, consultancy and assistance services, as well as those for the transfer of intellectual property rights, paid to a company in the same group, become entirely non-deductible.
Also, interest on loans granted by a company in the group would be deductible only up to the average interest rate in the country of the creditor, plus a maximum of one percentage point.
CCF argues that these provisions do not distinguish between real and artificial transactions and would lead to double taxation of the same amounts.
“The same amount would be taxed twice, including in Romanian groups. The company that provides the service pays tax on the income received, and the one that pays it can no longer deduct its cost. For example, for management services of 100,000 lei invoiced by a parent company in Cluj to its subsidiary in Iași, the group would pay profit tax twice: 16,000 lei to the parent company and 16,000 lei to the subsidiary. When the provider is located in another country, the income is taxed there, and the expense is no longer recognized in Romania,” the statement says.
CCF representatives warn that the measures could also affect banks, leasing companies and non-banking financial institutions, with possible consequences on the costs borne by clients.
“Banks and NFIs would be affected, and credit could become more expensive for companies and families. Banks, leasing companies and NFIs also finance themselves from the group they are part of, and the project does not exempt them, although the Fiscal Code already treats them separately in the rules on interest. The additional fiscal cost would most likely end up in the interest and installments paid by customers, for example by those who buy equipment or cars on lease. And Romania already has the lowest level of lending in the EU, compared to the size of the economy, according to the NBR”, specifies the source quoted by Agerpres.
At the same time, the organization draws attention to the impact that limiting the deductibility of interest could have on investment projects.
“Investments would become more expensive, and Romania less competitive. Many new projects, for example in energy, infrastructure or real estate, are financed through loans from shareholders or the group, especially during the construction phase. If interest becomes partially non-deductible, some projects are no longer profitable. And if management, IT or research and development services become more expensive for tax purposes, investors may choose other countries in the region for new activities,” the document states.
The Chamber of Tax Consultants recalls that Romania abandoned a similar measure in January 2026, following the recommendations of the Organization for Economic Cooperation and Development (OECD), and believes that the current project would introduce more severe restrictions.
“Romania has already abandoned, at the recommendation of the OECD, a similar but much milder measure. Art. 25 index 1 of the Fiscal Code limited these expenses to 1% of total expenses, only for companies with a turnover of under 50 million euros and with exceptions. It was repealed in January 2026, after less than a month of application, because the OECD signaled the risk of double taxation and discriminatory treatment. The current project goes much further: full non-deductibility, for all companies, without any exception, not even for transactions that ANAF has already confirmed as being at market price through advance pricing agreements,” the statement added.
In the organization’s opinion, the tax administration already has the necessary tools to identify and sanction artificial profit transfers, without introducing general restrictions.
“Fighting artificial profit shifting is a legitimate objective. The tools to achieve it already exist, and now they must be used better, not replaced with measures that would also affect taxpayers who comply with the rules,” said Adrian Luca, first vice-president of the Chamber of Tax Consultants.
For his part, Doru Dudaș, president of the CCF Tax Committee, criticized the lack of predictability of tax legislation.
“We are in a very difficult period from an economic point of view, and the macroeconomic indicators are being held with difficulty by the Government in an extremely fragile and dangerous balance. It is the twelfth hour in which Romania must stop legislating other new inventions of its own that are not based on taxation. The lack of tax predictability is already the greatest evil of the national economy,” said Doru Dudaș.
CCF calls for the non-adoption of the project in its current form, improvement of risk analyses and targeted fiscal controls, as well as consultation with the OECD, the business environment and the profession before introducing additional measures.